


Board Early to Avoid Delays: What the Global Airport Construction Boom Means for MEP
August 2026
 Back

Aviation is in the middle of one of the largest sustained infrastructure investment cycles in its history. This is not a post-pandemic rebound story. The funding is largely committed, the programmes are already moving and the scale of what is being built or planned is unlike anything the sector has seen before.
The driver is straightforward. Passenger demand has not just recovered from the disruption of the Covid-19 pandemic. It has exceeded it. US airports alone handled 981 million passengers in 2025, surpassing the previous record, and demand continues to grow month on month. Terminal infrastructure at many of the world’s busiest hubs was designed for volumes that were exceeded years ago. The industry is building to catch up.
The numbers reflect this. The global airport construction pipeline is currently valued at around $769 billion, with over 70% of that figure already in pre-execution or active construction phases. This is not a pipeline of future intentions. It is already underway.
What makes this cycle different from previous ones is its geographic spread and its ambition. Earlier waves of airport investment were concentrated in a handful of markets. This one is genuinely global.
- The three most active regions, Asia, the Middle East and North Africa and the US, together represent well over $400 billion in tracked airport construction activity, with record spending levels reported across all three markets.
- Latin America and the Caribbean, while smaller in absolute terms with a tracked pipeline of around $20 billion, show a broad spread of projects in planning and execution, from runway extensions to new terminal buildings. In the Caribbean in particular, public-private partnership deals continue to drive infrastructure additions at existing airports, with further opportunities expected to emerge across Central America.
Why the Margin for Error Is Narrower Than Ever
Building at scale has always carried risk. What has changed is the number of variables that are now moving at the same time, and the speed at which a single misjudgement compounds into a programme-level problem.
Construction cost escalation is running at 4 to 6% annually across most major markets as of mid-2026, with tariff-exposed trades running well above that baseline. Steel costs are up 15 to 25% year on year, with aluminium following at 8 to 10%. For a capital programme already in execution, these are significant budget events that cannot be absorbed without consequence.
The construction workforce is under equal pressure. In the US, 80% of construction firms report difficulty filling skilled positions, with the shortage most acute in electrical and mechanical trades. In the US alone, an additional 500,000 construction workers are needed in 2026 to meet projected demand. With around 40% of the skilled workforce approaching retirement age, the pressure is unlikely to ease any time soon.
Geopolitical instability has added a further layer. Ongoing tensions across the Middle East have kept energy prices elevated and raised fresh questions about long-term energy security, adding new uncertainty into freight costs and logistics timelines for airport programmes dependent on imported equipment and specialist materials.
The central issue for anyone commissioning a major airport programme today is not whether costs will rise. It is how unevenly and unpredictably those increases will appear across trades and material categories.
That unpredictability needs to be addressed before design decisions, procurement strategies and project programmes become fixed.
No Room for Error: The Realities of Live Terminal Construction
Airports cannot close. That single fact shapes everything about how construction within a live terminal is planned, sequenced and delivered. Unlike a new-build facility on open land, an airport expansion has to be threaded around active passenger flows, airline schedules, security zone interfaces and airfield operations. Construction sequences are built around night possessions and micro-phases, with temporary systems standing in while permanent ones are upgraded. The margin for error is narrow, and the consequences of getting the sequence wrong are immediate and public.
Building services sit at the heart of this complexity. Terminal ceiling voids contain some of the densest concentrations of MEP infrastructure found anywhere in construction: HVAC distribution, electrical containment, fire detection, life safety systems and baggage handling controls all competing for the same space.
When an MEP contractor arrives after the design has been substantially completed, they inherit coordination problems that were baked in before they were appointed. In a live airport environment, rework of this kind carries both a cost and an operational consequence.
The fixed opening date makes this harder still. Most airport programmes carry contractual commitments to airline tenants, regulatory bodies and government stakeholders that cannot move. A 40-week equipment lead time that was not identified until detailed design is complete does not become a planning problem. It becomes a programme failure. The penalty for late MEP appointment on an airport project is measurably higher than on most other building types.
Mission-Critical: The Expanding Role of Building Services in Aviation
Airports are no longer simply large public buildings with complex services. They are becoming energy infrastructure in their own right. Electric ground support equipment is now standard at many major airports, with operators investing in charging infrastructure across airside operations. At the largest airports, peak power demand from ground support electrification alone can reach up to 20 megawatts.
Alongside this, major airports including San Francisco, Denver, Istanbul, Athens and Cochin (India) are pursuing full or near-full electricity independence through large-scale solar, battery storage and long-term renewable energy agreements. The shift from gas-fired central plant to fully electric building systems is no longer a future ambition. It is already under construction at several leading airports globally.
The consequences of getting these decisions wrong are immediate and public in a way that failures in other building types simply are not. A UPS cooling fan failure at Manila’s Ninoy Aquino International Airport in 2023 effectively shut down the airport. In 2026, a baggage handling system failure at Heathrow left 20,000 bags misplaced, causing days of disruption. These are not isolated incidents. Operational failures in airport legacy infrastructure are estimated to cost the aviation industry billions of dollars annually.
Power distribution, UPS, baggage handling controls and HVAC in security-critical zones. These are precisely the systems that building services engineers design, specify and commission.
The performance of these systems over decades is largely determined by decisions made during the design stage, which is precisely why the involvement of the right people at the right stage matters more here than almost anywhere else in construction.
Delivering Airport Infrastructure Across the Caribbean
Preventing failures of this kind requires more than a technically sound design. It requires practical delivery experience, an understanding of how airport systems interact and the ability to coordinate specialist contractors, equipment and supply chains within demanding operational environments.
Update Group’s Caribbean airport experience spans three major projects:
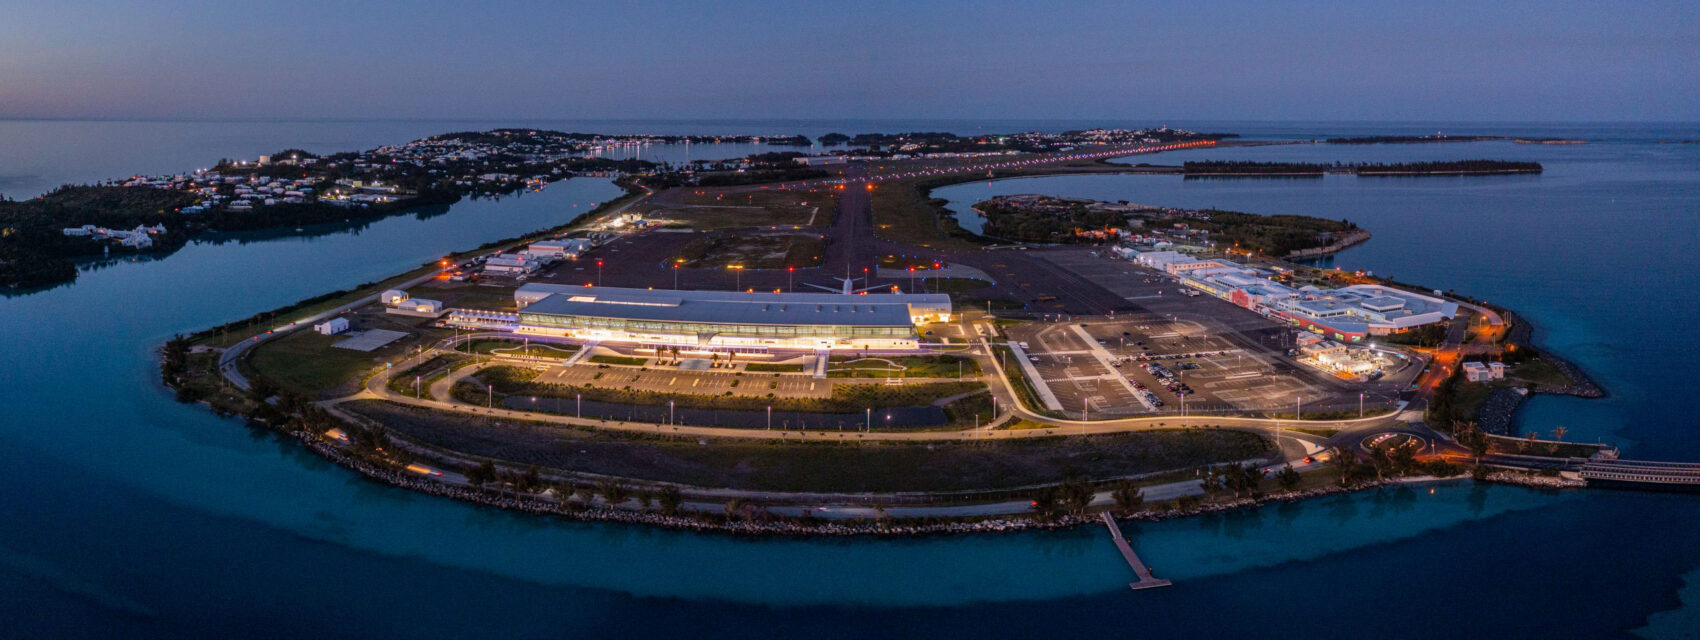
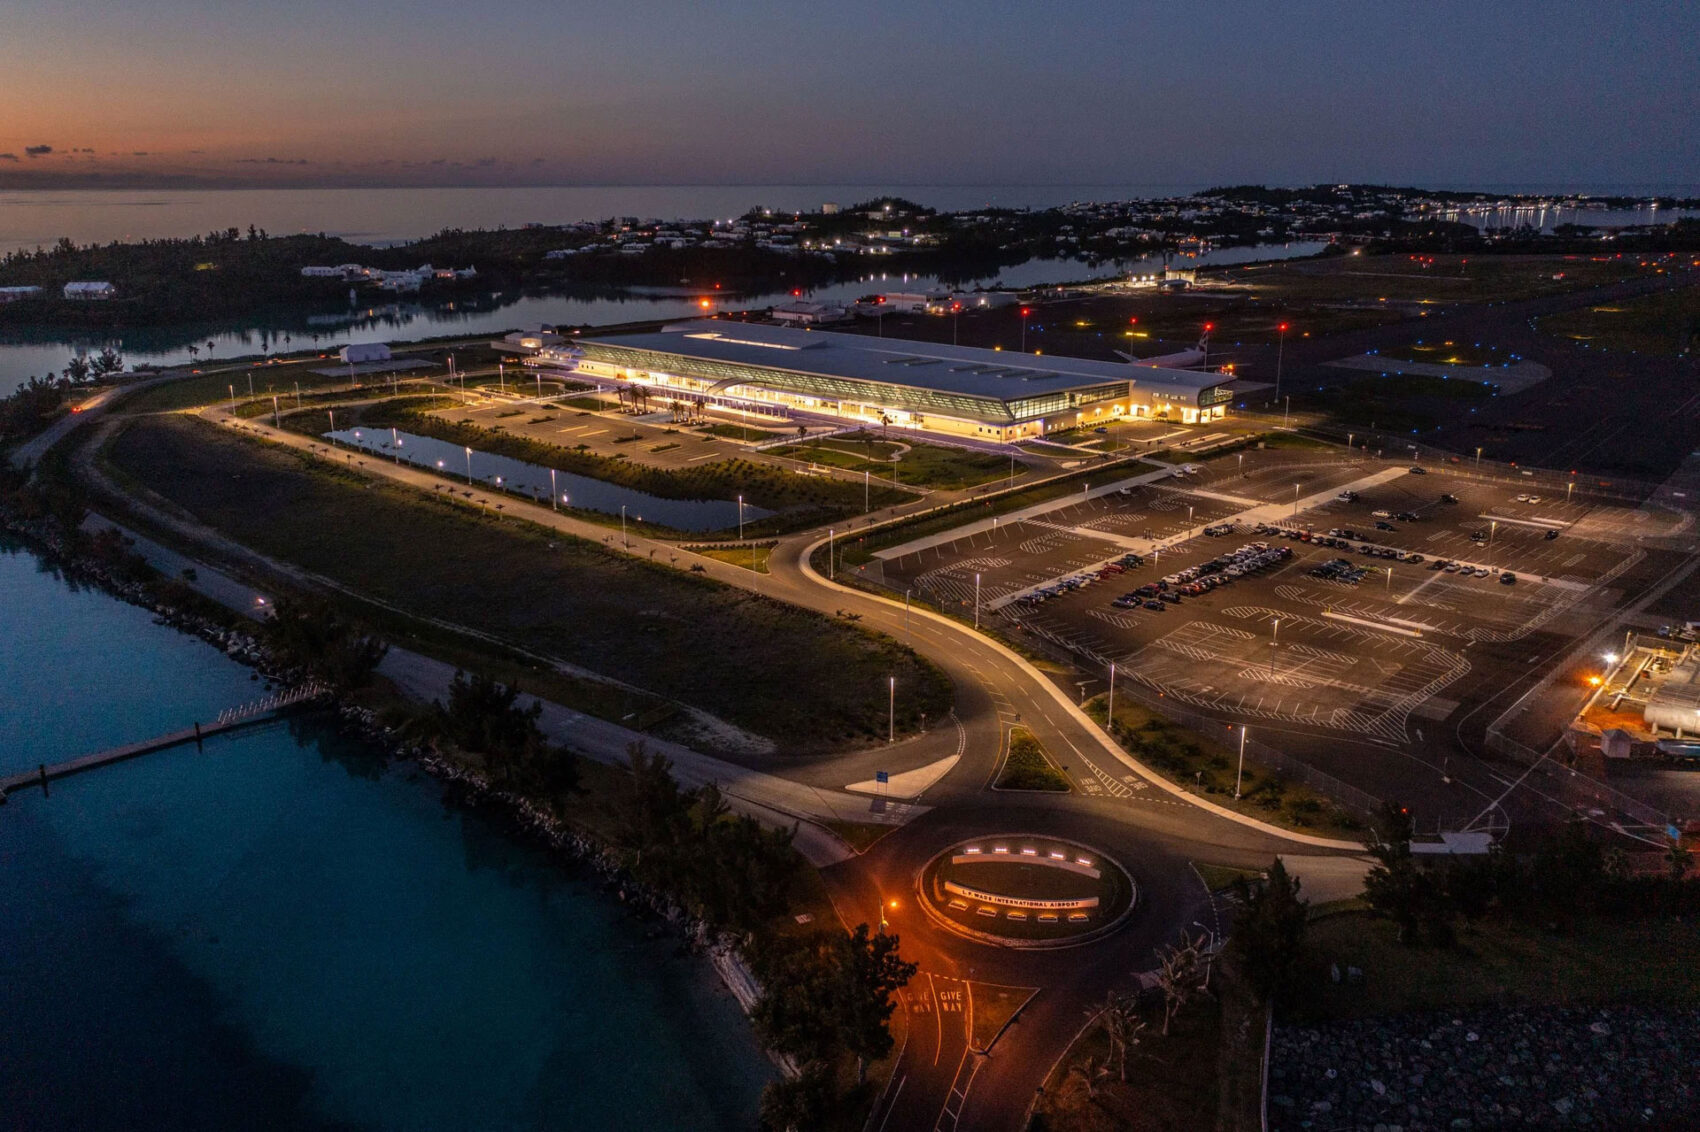
- LF Wade International Airport, Bermuda: In partnership with Aecon Group Inc., Update Group delivered the complete mechanical, electrical, IT and fire safety systems for a new 280,000 sq ft terminal designed to handle up to two million passengers annually.
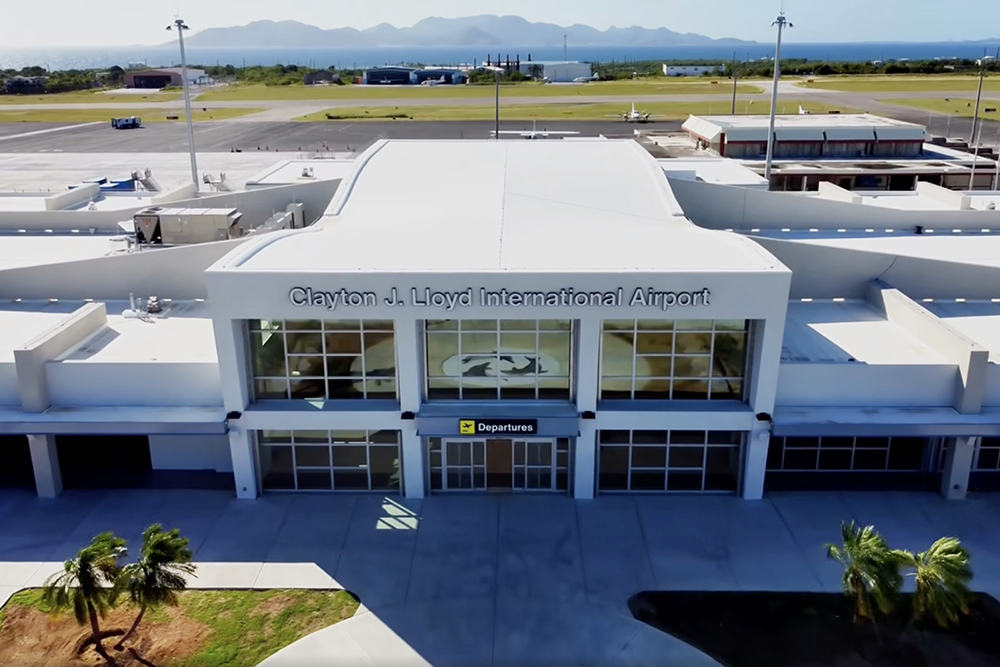
- Clayton J. Lloyd International Airport, Anguilla: Update Group completed the full MEP package for the new 50,000 sq ft passenger terminal.
- Cyril E. King Airport, St. Thomas, U.S. Virgin Islands: Update Group is providing pre-construction services and the complete building services package for an expansion that will increase capacity to around 900,000 passengers annually.
Together, these projects have given Update Group a practical understanding of airport delivery across the Caribbean.
This is a market where delivery experience, supply chain relationships and an understanding of operationally complex environments matter as much as technical capability. It is also a region where early coordination and informed procurement make a decisive difference to programme certainty.
Writing in the latest edition of Airport World, Anthony Le Caherec, Head of the Airport Business Line at Bouygues Construction, noted that airports are increasingly recognising the value of bringing experienced contractors into projects at an early stage. It is a view that aligns closely with what Update Group has seen across its own airport programmes.
The Conversation Worth Having Now
Programmes are moving. Procurement windows are closing. If you are involved in planning, funding or delivering a major airport programme, Update Group would welcome the conversation. With direct experience across airport projects in the Caribbean and a delivery model built around early engagement, we work with clients from the earliest stages to reduce risk before it becomes a cost.
Read More
See how early engagement and a structured delivery approach help reduce risk, improve cost certainty and keep projects on programme.
Related
Selected airport projects, completed and in progress, where early engagement and coordinated delivery have been critical to programme and operational success.


Bermuda
Anguilla
St. Thomas, U.S. Virgin Islands